Essential Insights on Merged Plans
Key Steps for Assessing Your Debt Situation
Creating a successful merged plan in the United Kingdom begins with a comprehensive review of your current debts. This critical process involves examining existing agreements and interest rates to verify that debt consolidation is a suitable option. By conducting this assessment, you not only clarify the total debt amount but also identify which debts impose the greatest financial burden. This strategic method allows you to effectively plan your debt merging journey.
Understanding the different types of debts you possess, along with their interest rates and repayment terms, is essential. This knowledge empowers you to determine if a merged plan could lead to a more manageable repayment schedule. It establishes a foundation for evaluating potential savings on interest payments, which can significantly enhance your overall financial health in the long term.
Determining Your Eligibility for Merged Plans
Lenders evaluate several criteria when assessing your eligibility for a merged plan. One of the primary factors they consider is your income stability, which indicates your ability to meet repayment obligations. They also review your current credit commitments to ensure that the merged plan aligns with your financial situation.
The evaluation process typically involves an analysis of your credit history. Lenders look for signs of responsible borrowing and repayment behaviour. A strong credit profile can improve your chances of approval, while a history of missed payments may complicate your application process. Understanding these eligibility factors equips you to make a compelling case when applying for a merged plan.
Understanding Common Structures of Merged Plans
Merged plans usually consist of fixed monthly payments distributed over a specific timeframe. This structure aims to simplify your financial situation by consolidating multiple debts into one manageable repayment schedule. Various providers in the United Kingdom offer these plans, which can be tailored to meet individual circumstances.
Typically, these plans feature straightforward terms regarding interest rates and repayment periods. By merging debts, borrowers may lower their overall monthly payments and relieve the stress associated with managing multiple creditors. This clarity is particularly beneficial for long-term financial planning and stability.
Short-Term Effects of Merged Plans on Your Credit Score
What Impact Does the Application Process Have on Your Score?
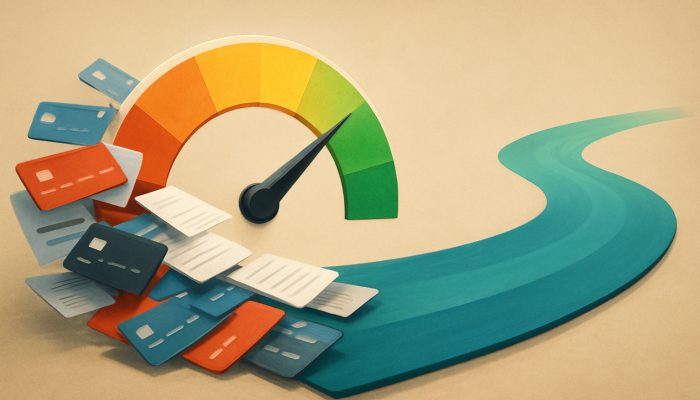
When you apply for a merged plan, it initiates hard inquiries on your credit file. These inquiries can lead to temporary decreases in your credit score, which may be visible to lenders during the initial approval phase. While such dips are common, it is important to understand that they are generally short-lived.
The degree of impact on your credit score can vary based on several factors, including your overall credit profile and the number of recent inquiries. Being aware of this can help you manage your expectations as you navigate the application process. Concentrate on the long-term benefits of a merged plan rather than the immediate fluctuations in your score.
What Are the Consequences of Closing Old Accounts?
As part of the debt merging process, you may need to close old credit accounts. This action can lower your available credit lines, which might negatively affect your credit score calculations. Credit scoring agencies in the United Kingdom factor in total available credit when assessing risk, so a reduction could lead to a lower score.
Closing accounts can also streamline your financial management. Fewer accounts can reduce complexity, making it easier to keep track of payments. It requires a careful balance; while you may experience a short-term decline in your score, the long-term advantages of a merged plan can outweigh these initial challenges.
How Will Your Credit Utilisation Ratio Change?
Consolidating credit accounts can alter your credit utilisation ratios, which are vital for determining your credit score. When balances are merged, your overall credit utilisation may improve, leading to potential changes in your score. This effect is particularly noticeable during the transition period when new balances are reported to credit agencies.
Credit utilisation is crucial in credit scoring models; a lower ratio typically indicates better financial health. After merging, it is advisable to monitor your credit report closely to understand how these changes impact your score. Adjusting your spending habits after the merger can further enhance your credit profile.
Implications of Merged Plans on Your Payment History
How to Track Your Payment Consistency
Making regular repayments under a merged plan contributes to building a positive payment history over time. This information is recorded by UK credit reference agencies and reflects responsible financial behaviour. A solid payment history can significantly boost your credit score, making you a more appealing option for future lenders.
Establishing a consistent payment pattern is essential. Timely payments indicate to lenders that you are a reliable borrower, which can lead to improved credit offers in the future. As your payment history strengthens, it becomes a valuable asset within your overall credit profile.
What Are the Risks of Missing Payments?
Although a merged plan simplifies repayments, missed payments present a significant risk. Any missed payments are reported swiftly and can remain on your credit record for several years. This negative information can severely limit your future borrowing options within the United Kingdom.
To mitigate this risk, staying organised and ensuring timely payments is crucial. Setting up direct debits or reminders can assist in maintaining consistency. Understanding the consequences of missed payments can motivate you to adhere strictly to your repayment schedule.
How to Build a Positive Credit History
Consistently making on-time payments through a merged plan enhances your overall credit profile. UK scoring models reward reliability, and a solid payment history can unlock better credit opportunities. This aspect of credit scoring underscores the importance of maintaining a consistent repayment schedule.
Building a positive history takes time; however, the rewards are considerable. As your payment history improves, lenders may be more willing to extend credit on favourable terms. This ongoing process of enhancing your credit profile is crucial for your long-term financial health.
What Adjustments Occur to Your Credit Score?
Frequent updates concerning merged plan payments enable UK credit scoring systems to adjust scores dynamically based on recent behaviour. As you make consistent payments, your credit score can improve, reflecting your increasing financial responsibility.
Monitoring these adjustments is essential. Credit scores are not static; they fluctuate based on your financial actions. Staying informed about how your payments impact your score empowers you to make well-informed decisions moving forward.
Expert Insights on the Impact of Merged Plans on Your Credit Score
What Factors Influence Score Calculations?
Numerous elements affect credit score calculations, particularly regarding merged plans. For instance, individuals with high levels of prior debt may experience different outcomes compared to those with lower debt levels after merging. Real-world examples from the UK illustrate this variability.
Those burdened with substantial debt may notice a more significant initial decline in their scores due to hard inquiries and account closures. Conversely, individuals with manageable debt might experience a smoother transition. Understanding these dynamics can help you navigate the implications of a merged plan more effectively.
How Do Lenders Report Credit Behaviour?
Once you initiate a merged plan, it is essential to review reports from credit agencies such as Experian. Monitoring your credit report allows you to identify any discrepancies or errors. These reports provide insights into how lenders perceive your creditworthiness after the merger.
Regularly checking your credit report also helps you understand how your merged plan impacts your score. Taking proactive measures, such as disputing inaccuracies, can enhance your credit profile. Being vigilant in monitoring your credit is crucial for long-term financial success.
What Is the Timeline for Credit Score Recovery?
The timeline for credit score recovery following the completion of a merged plan can vary for each individual. Generally, those who maintain consistent payments can expect improvements within a few months. The specific recovery duration may depend on individual circumstances, including previous credit behaviour.
Expert analysis suggests that while some may recover quickly, others may take longer due to factors such as missed payments or high debt levels. Understanding these timelines can help you set realistic expectations for your financial recovery journey.
How Do Merged Plans Influence Mortgage Applications?
Participating in a merged financial arrangement can impact your chances of securing home loans. Lenders in the United Kingdom may view merged plans as a risk factor, particularly if your credit score has declined during the process. Strategies exist to mitigate these negative effects on your approval likelihood.
Improving your credit score through consistent repayments and monitoring your credit report can make you more appealing to lenders. Presenting a clear financial plan to prospective lenders can demonstrate your commitment to responsible borrowing, potentially alleviating concerns regarding your merged plan.
Identifying the Long-Term Consequences of Merged Plans
How Are Credit Limits Adjusted?
Merged plans often lead to reduced limits on remaining accounts. UK credit models incorporate these adjustments into future affordability assessments. A lowered credit limit can affect your ability to secure new credit, as lenders may interpret this as a sign of increased risk.
Nevertheless, proficient management of a merged plan can enhance your creditworthiness over time. As you demonstrate responsible financial behaviour, lenders may gradually increase your credit limits, positively impacting your overall credit profile. This long-term perspective is crucial for achieving financial stability.
What Restrictions May You Face When Accessing New Credit?
Borrowers may face limitations on new loans during the duration of a merged plan. This restriction is often reflected in UK credit decisions, as lenders may hesitate to extend credit to individuals currently engaged in a merged arrangement. Understanding these constraints is essential for managing your financial future.
During this period, it is wise to focus on rebuilding your credit. By making consistent payments and avoiding new debt, you can improve your credit profile. This proactive approach can position you favourably for future borrowing opportunities once the merged plan concludes.
How Can You Strengthen Your Overall Credit Profile?
Successfully completing a merged plan can enhance your credibility with lenders in the United Kingdom over extended periods. As you show a commitment to repaying your debts, your overall credit profile strengthens, making you a more attractive candidate for future credit products.
This long-term enhancement of your profile is vital for achieving financial goals. A robust credit history, cultivated through responsible financial behaviour, can lead to better interest rates and loan terms. The effort invested in managing a merged plan pays off as you progress towards a healthier financial future.
Research-Backed Benefits of Merged Plans on Credit Scores
How Do Merged Plans Reduce Credit Inquiries?
After merging debts, borrowers typically experience fewer applications for new credit. This reduction in inquiries helps stabilise scores, as indicated by data patterns observed in the United Kingdom. A lower frequency of inquiries signals to lenders that you are managing your credit responsibly.
This stability can facilitate gradual improvements in credit scores over time. As your credit profile becomes more consistent, lenders may view you as a lower risk. Understanding the relationship between inquiry frequency and credit scores can assist you in making better-informed borrowing decisions.
What Metrics Indicate Debt Reduction Success?
Research suggests that merged plans can accelerate debt repayment, leading to improved metrics monitored by credit agencies in the United Kingdom. As debts are consolidated, borrowers often find it easier to manage payments, lowering the likelihood of missed payments and defaults.
This positive trend not only enhances credit scores but also cultivates better financial habits. By prioritising debt reduction through a merged plan, individuals can pave the way for a more sustainable financial future. The benefits extend beyond immediate score improvements, promoting long-term financial stability.
What Improvements in Financial Behaviour Can You Expect?
- Enhanced budgeting skills
- Increased financial awareness
- Improved consistency in payments
- Greater confidence in managing finances
- Ability to identify and avoid future debt pitfalls
- Stronger relationships with lenders
- Better understanding of credit scores
These positive behavioural changes often arise following plan approval in the United Kingdom. As individuals adapt to their new financial situations, they develop skills that contribute to healthier financial habits.
How Can Credit Utilisation Ratios Be Affected?
What Are the Methods for Calculating Ratios?
Lower balances resulting from merged plans directly enhance utilisation figures used in UK scoring systems. Credit utilisation is calculated by dividing your total outstanding credit by your total available credit. A lower ratio signifies better financial management and can positively influence your credit score.
Maintaining a healthy utilisation ratio is vital for long-term credit health. After merging debts, it is advisable to keep an eye on your spending to ensure that your ratio stays within a favourable range. This proactive approach can help you avoid potential pitfalls and maintain a strong credit profile.
What Are the Effects of Balance Transfers?
Transferring debts through a merged plan alters your credit ratios, which agencies monitor closely for UK consumers. As balances shift, your overall credit utilisation may change, thereby impacting your score. Understanding these dynamics is essential for effectively managing your credit.
Keeping a close watch on how balance transfers affect your credit profile can provide valuable insights. Tracking your utilisation ratio helps you make informed decisions regarding future borrowing and spending behaviours. This awareness promotes better financial management in the long run.
How Can You Target Optimal Ratios?
Maintaining credit utilisation ratios below specific thresholds supports better scores in UK evaluations. It is generally recommended to keep your ratio below <a href="https://www.debtconsolidationloans.co.uk/using-a-new-loan-to-cut-utilisation-effective-strategies/">30%</a> to enhance your creditworthiness. A lower ratio indicates that you are not overly reliant on credit, which lenders view favourably.
Setting this target can guide your financial behaviours after a merger. By being mindful of your spending and repayment practices, you can ensure that your credit utilisation remains advantageous. This discipline is essential for achieving enduring credit health.
What Are the Best Strategies for Recovery After Merging?
What Are Effective Monitoring Techniques?
Regular checks with UK credit agencies enable early detection of any score fluctuations following your plan. Monitoring your credit report keeps you informed about how your merged plan affects your score. This proactive approach allows you to address any issues promptly.
Utilising credit monitoring tools can also enhance your understanding of your financial health. Many services provide alerts for significant changes, allowing you to stay on top of your credit status. Vigilance in credit monitoring can facilitate a smoother recovery process.
How Can You Build New Credit Responsibly?
- Secured credit cards
- Small personal loans
- Store credit cards
- Credit-builder loans
- Co-signed loans
- Products from credit unions
- Peer-to-peer lending options
These alternatives can offer essential benefits for rebuilding credit profiles in the United Kingdom. By managing new credit responsibly, individuals can demonstrate their commitment to improving their creditworthiness.
Why Is Seeking Professional Guidance Important?
Consulting with authorised advisers can facilitate effective recovery tailored to UK regulations. These professionals provide personalised strategies for managing your credit following a merger. Their expertise helps you navigate complex financial landscapes and make informed decisions.
Engaging with financial advisers empowers you to take control of your financial future. By understanding the intricacies of credit management, you can develop a sustainable plan for rebuilding your credit and achieving long-term financial objectives.
What Are the Best Ongoing Credit Monitoring Practices?
How to Conduct Regular Report Reviews?
Annual checks using statutory reports assist in tracking changes resulting from merged plans in the United Kingdom. These evaluations offer insights into how your credit profile evolves and enable you to identify areas needing improvement. Staying informed about your credit status is key to effective management.
Utilising statutory reports ensures access to accurate information. This transparency helps you spot discrepancies or errors that could negatively affect your score. Regularly reviewing your credit report is a fundamental step in preserving a healthy credit profile.
How to Utilise Score Improvement Tools?
Using approved simulators can provide insights into ongoing impacts within UK frameworks. These tools allow you to explore various financial scenarios, helping you understand how different actions influence your credit score. This understanding can guide your decision-making process.
Engaging with score improvement tools can also clarify the credit scoring process. By gaining a deeper understanding of how your actions affect your score, you can make more informed financial choices. This proactive approach is crucial for achieving long-term financial health.
What Are the Benefits of Setting Up Alert Systems?
Enabling notifications ensures you are promptly informed of any updates from credit agencies in the United Kingdom. These alerts can notify you of significant changes to your credit report, helping you stay on top of your financial status. Being proactive in this regard can prevent future issues.
Establishing alerts encourages you to engage consistently with your credit profile. This ongoing diligence fosters a greater understanding of your financial health and empowers you to take action when necessary. Maintaining a proactive mindset is essential for sustaining a robust credit score.
Why Is Long-Term Credit Monitoring Important?
By reviewing credit reports from the past several years, consumers in the United Kingdom can observe how their financial choices impact their overall credit standing. This longitudinal perspective enables a deeper understanding of credit behaviour and its long-term consequences.
Monitoring your credit history over time can unveil patterns and trends. Recognising these trends can inform your future financial decisions and help you avoid potential pitfalls. This comprehensive approach to credit management is vital for achieving lasting financial stability.
Frequently Asked Questions
What is a merged plan?
A merged plan consolidates several debts into a single repayment structure, simplifying your financial obligations and potentially lowering monthly payments.
How does a merged plan impact my credit score?
Initially, a merged plan can lead to a temporary decline in your credit score due to hard inquiries and account closures; however, consistent payments can improve it over time.
Can I apply for credit while enrolled in a merged plan?
Yes, but you may face restrictions on new loans during the plan’s duration, as lenders might view you as a higher risk.
How long does it typically take to see improvements in my credit score?
Improvements can often be observed within a few months of making consistent payments, although the exact timeline varies based on individual circumstances.
Will closing old accounts negatively affect my credit score?
Yes, closing old accounts can reduce your available credit, which may harm your credit score.
What actions should I take if I miss a payment on my merged plan?
Missed payments can adversely affect your credit score, so it is crucial to catch up as soon as possible and communicate with your lender.
Is it possible to rebuild my credit after completing a merged plan?
Certainly. Responsibly managing new credit and monitoring your credit report can assist you in recovering and enhancing your score.
What advantages are there to monitoring my credit report?
Monitoring your credit report allows you to identify errors, track changes, and stay informed about your credit status, which is crucial for effective management.
How can I enhance my credit utilisation ratio?
You can improve your ratio by paying down existing debts and refraining from new credit applications while participating in a merged plan.
Should I seek professional advice regarding my credit situation?
Yes, consulting with authorised financial advisers can provide tailored strategies for managing your credit and enhancing your financial health.
Visit our Facebook profile for more insights!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk